HOUSES AND APARTMENTS
Featured homes
A few furnished homes for a Houston extended stay, a move, or an insurance stay.
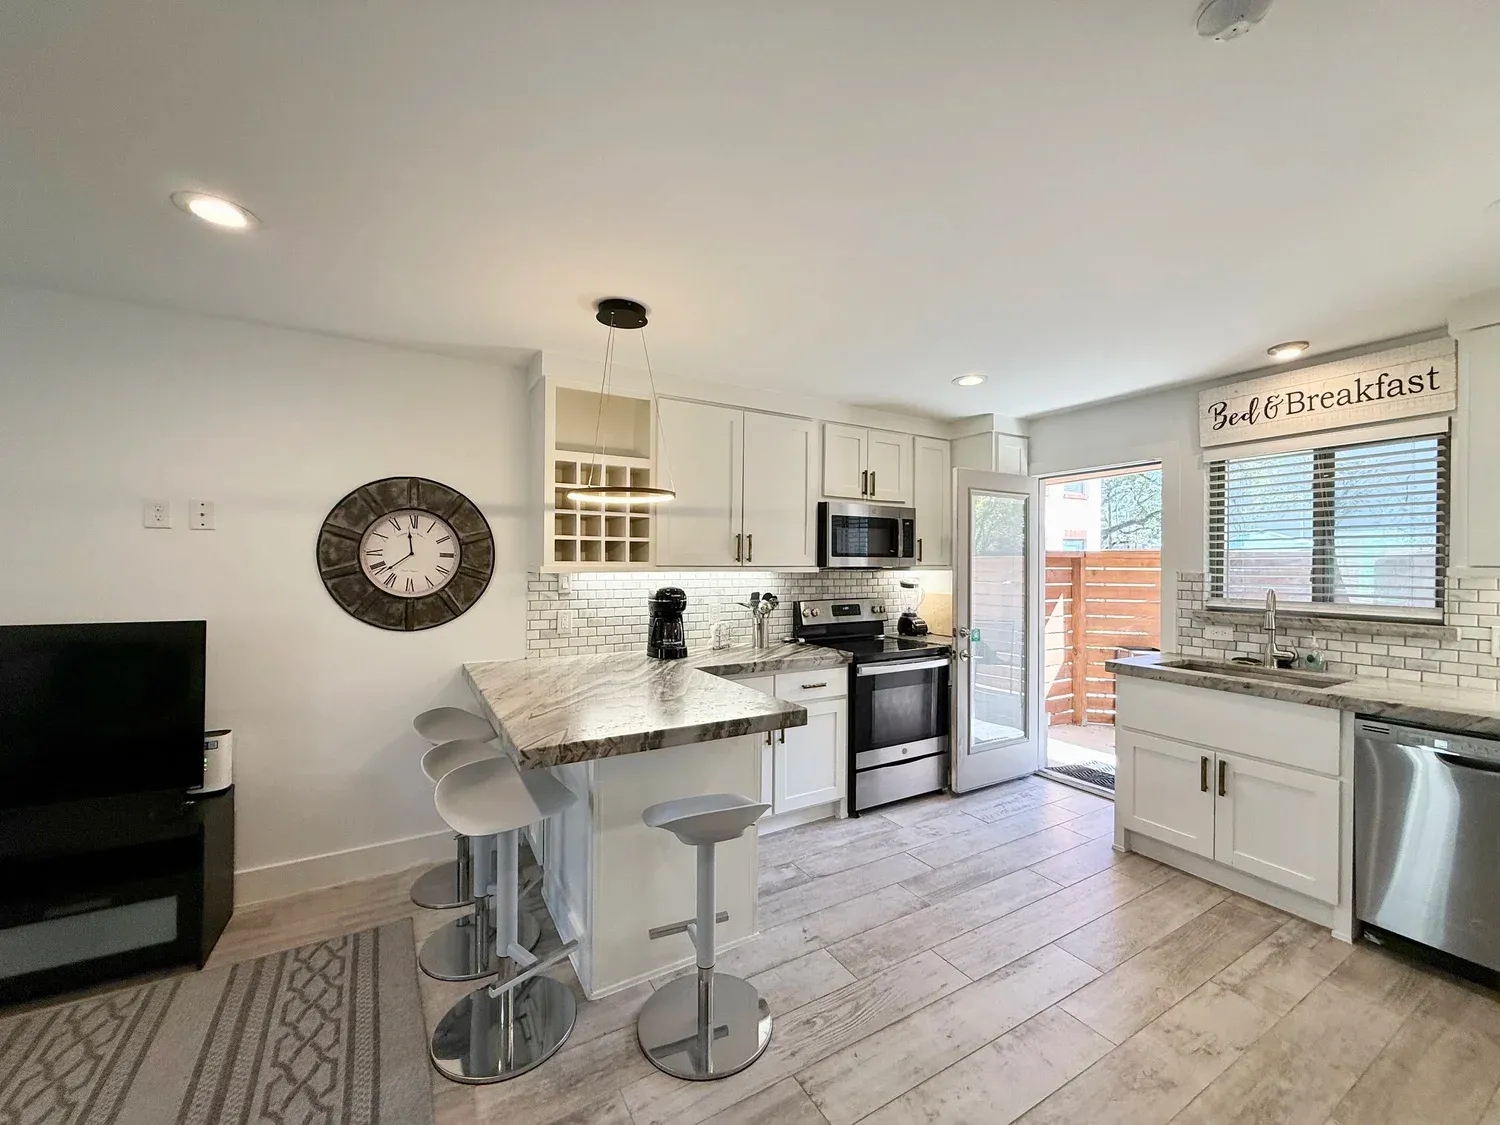
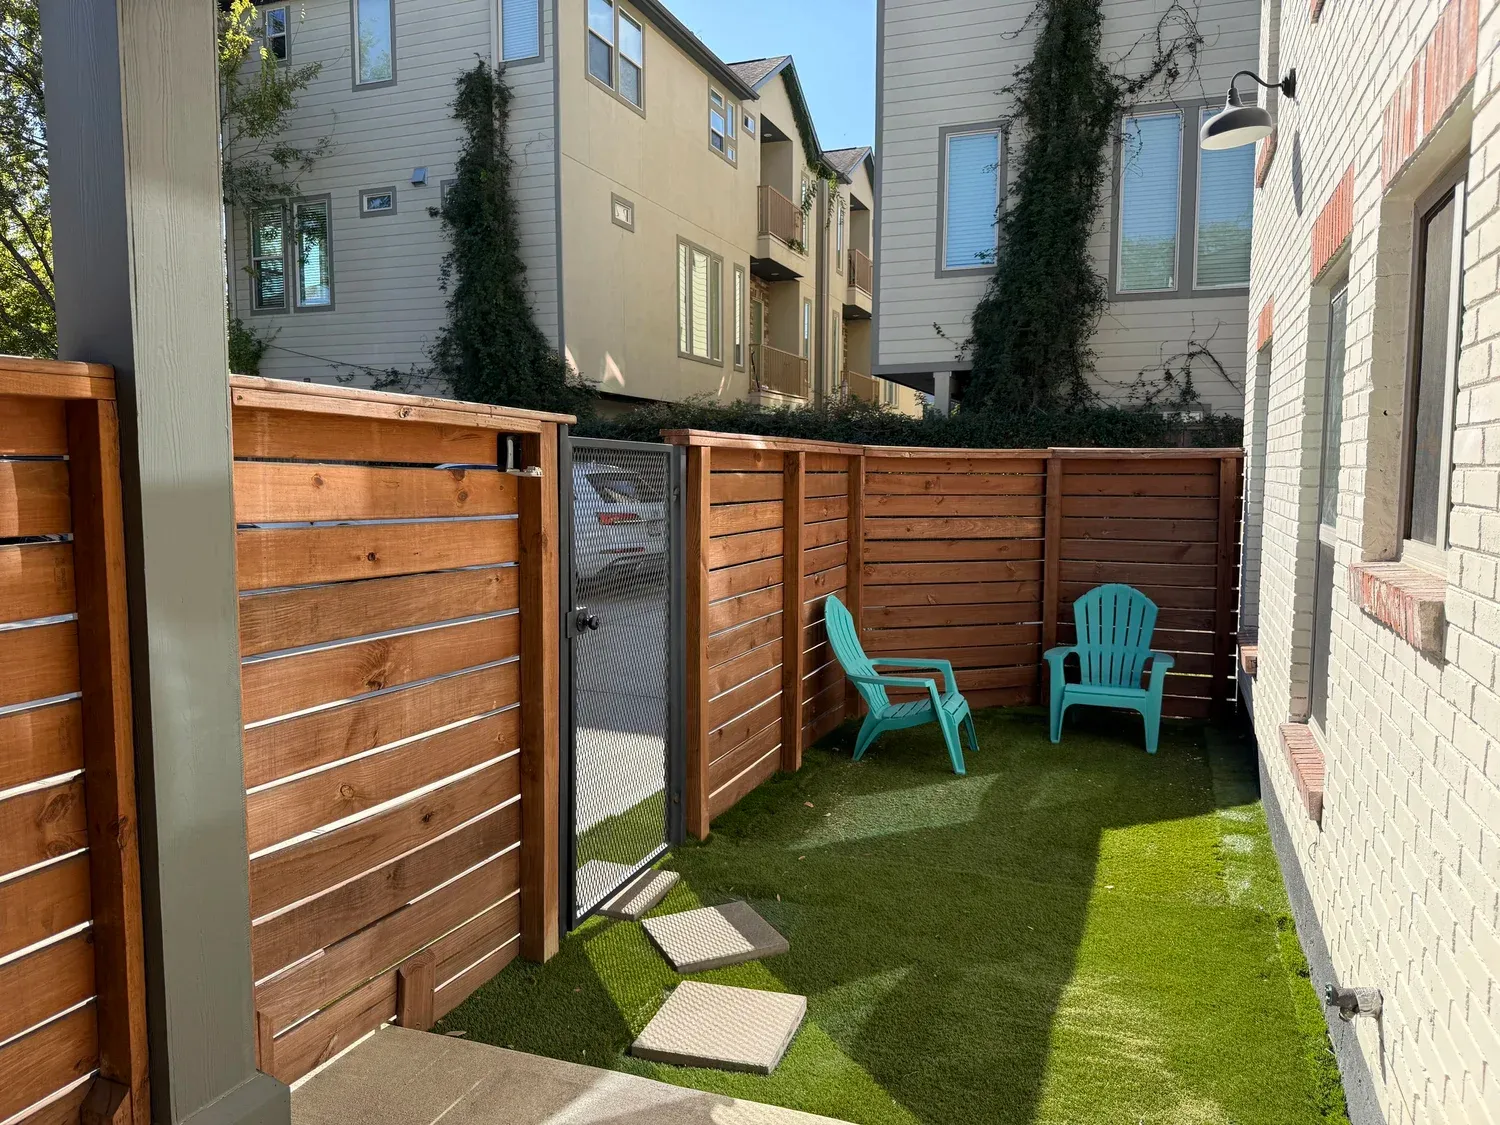
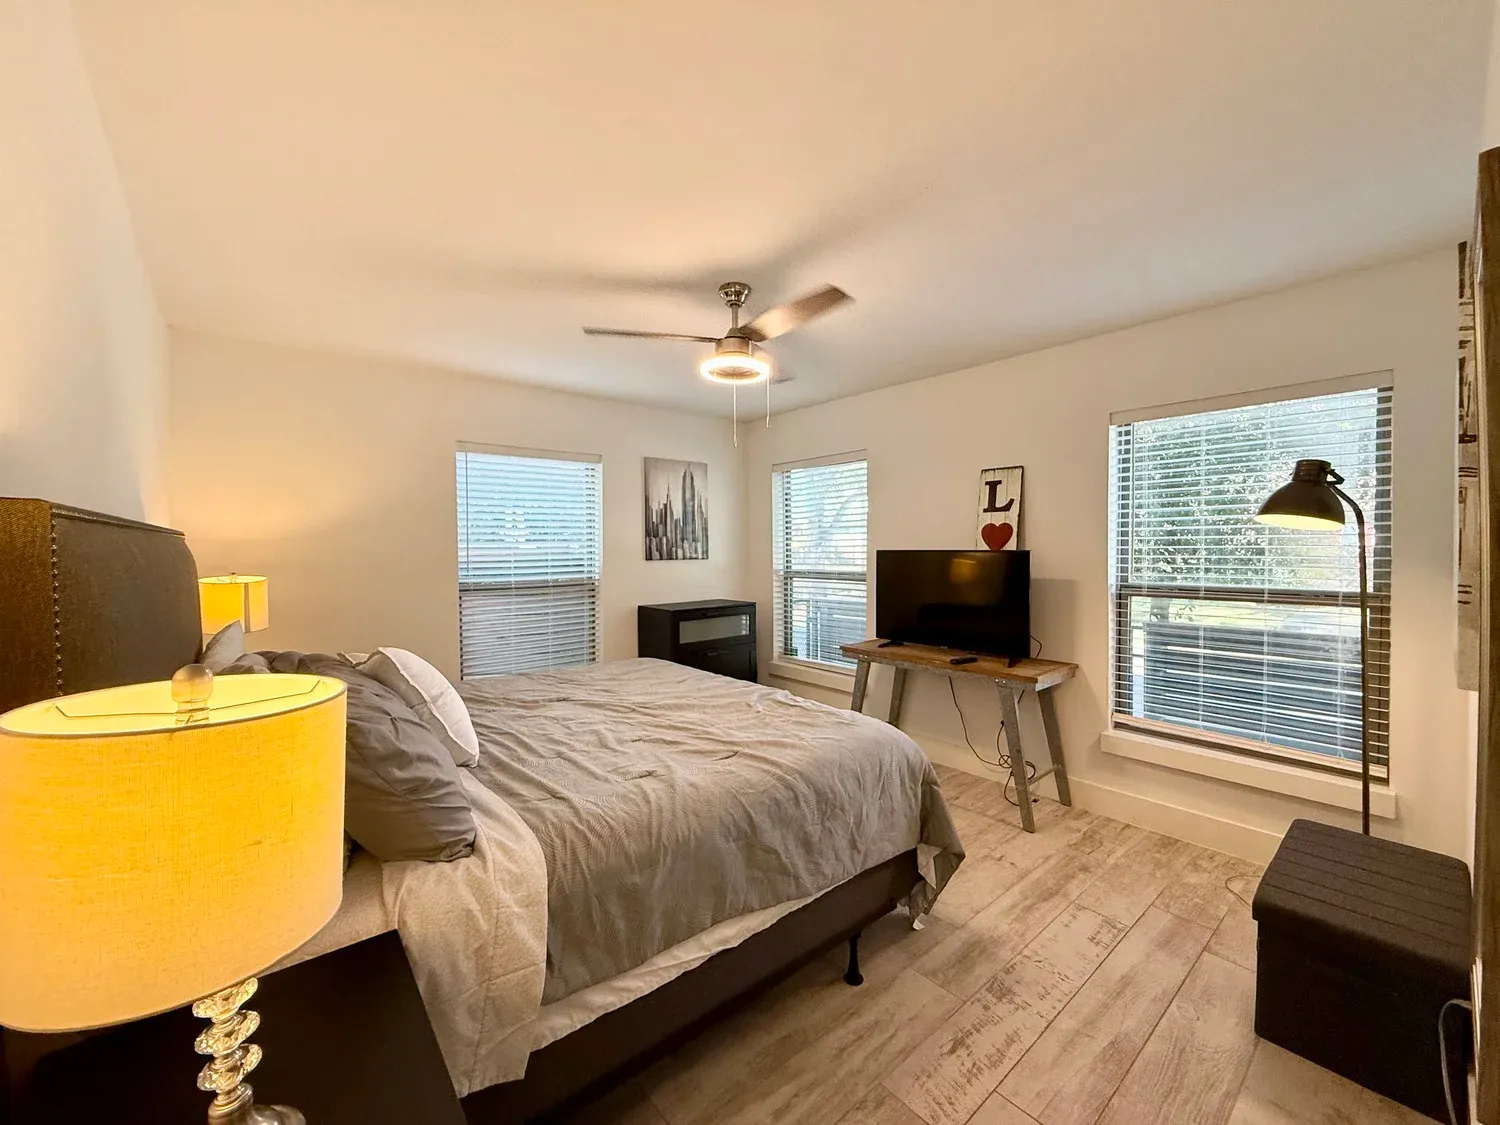
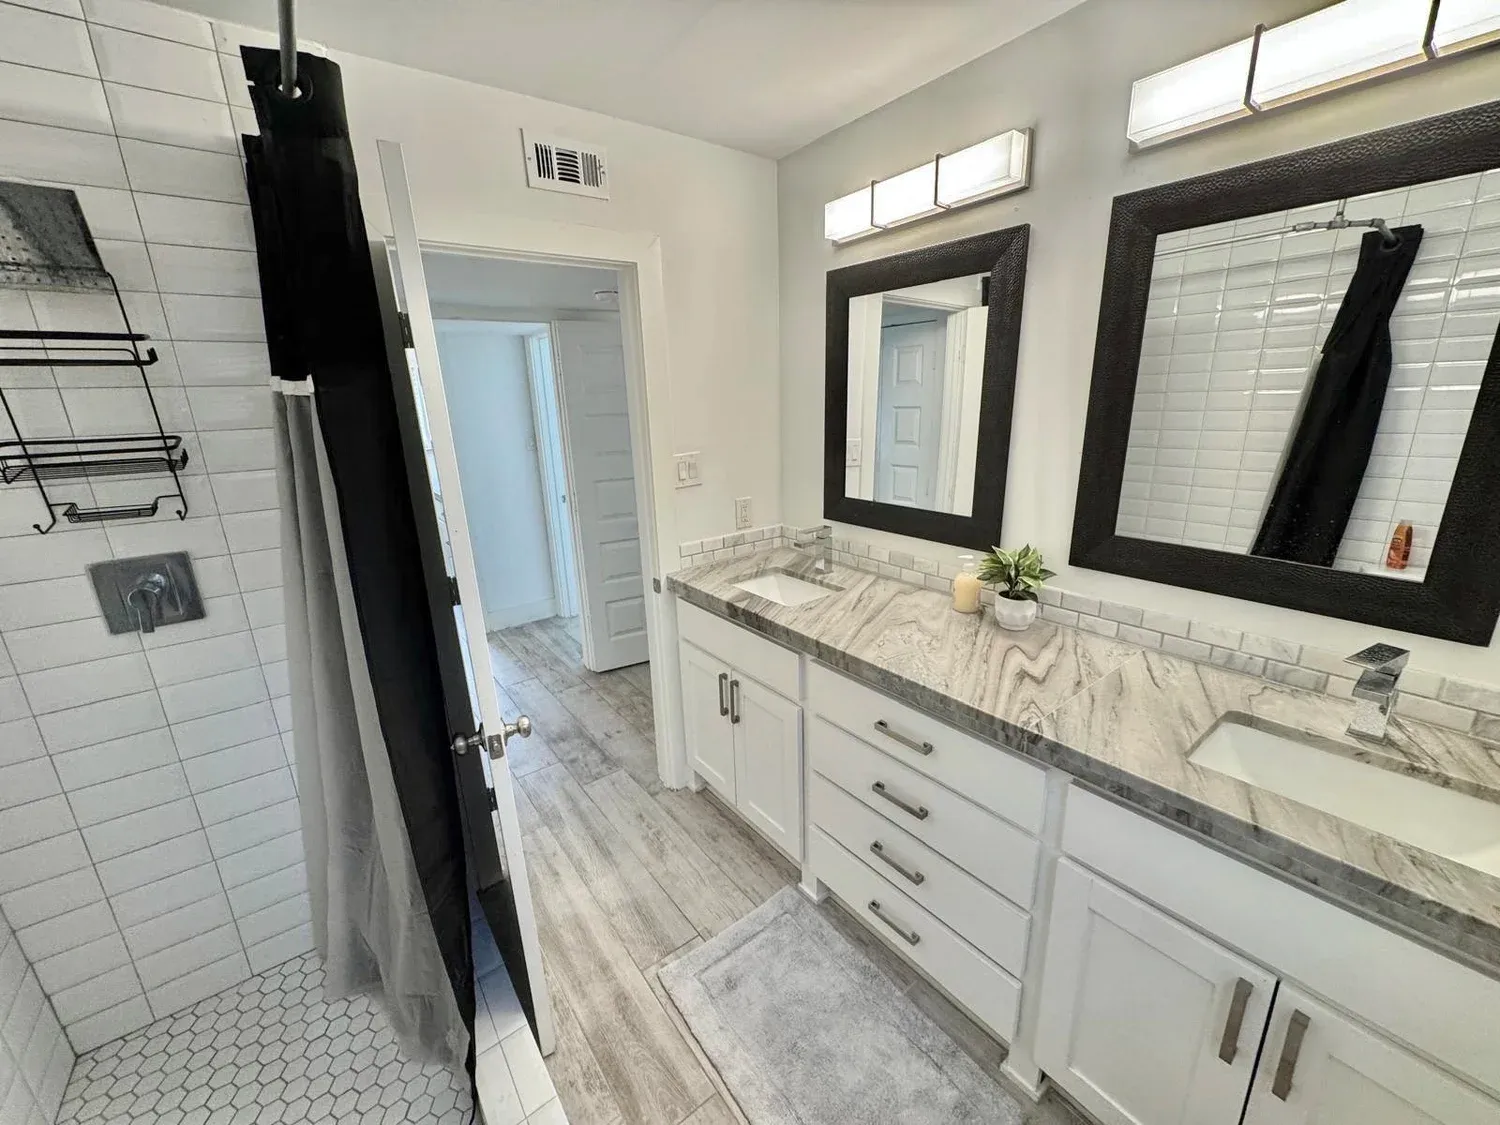
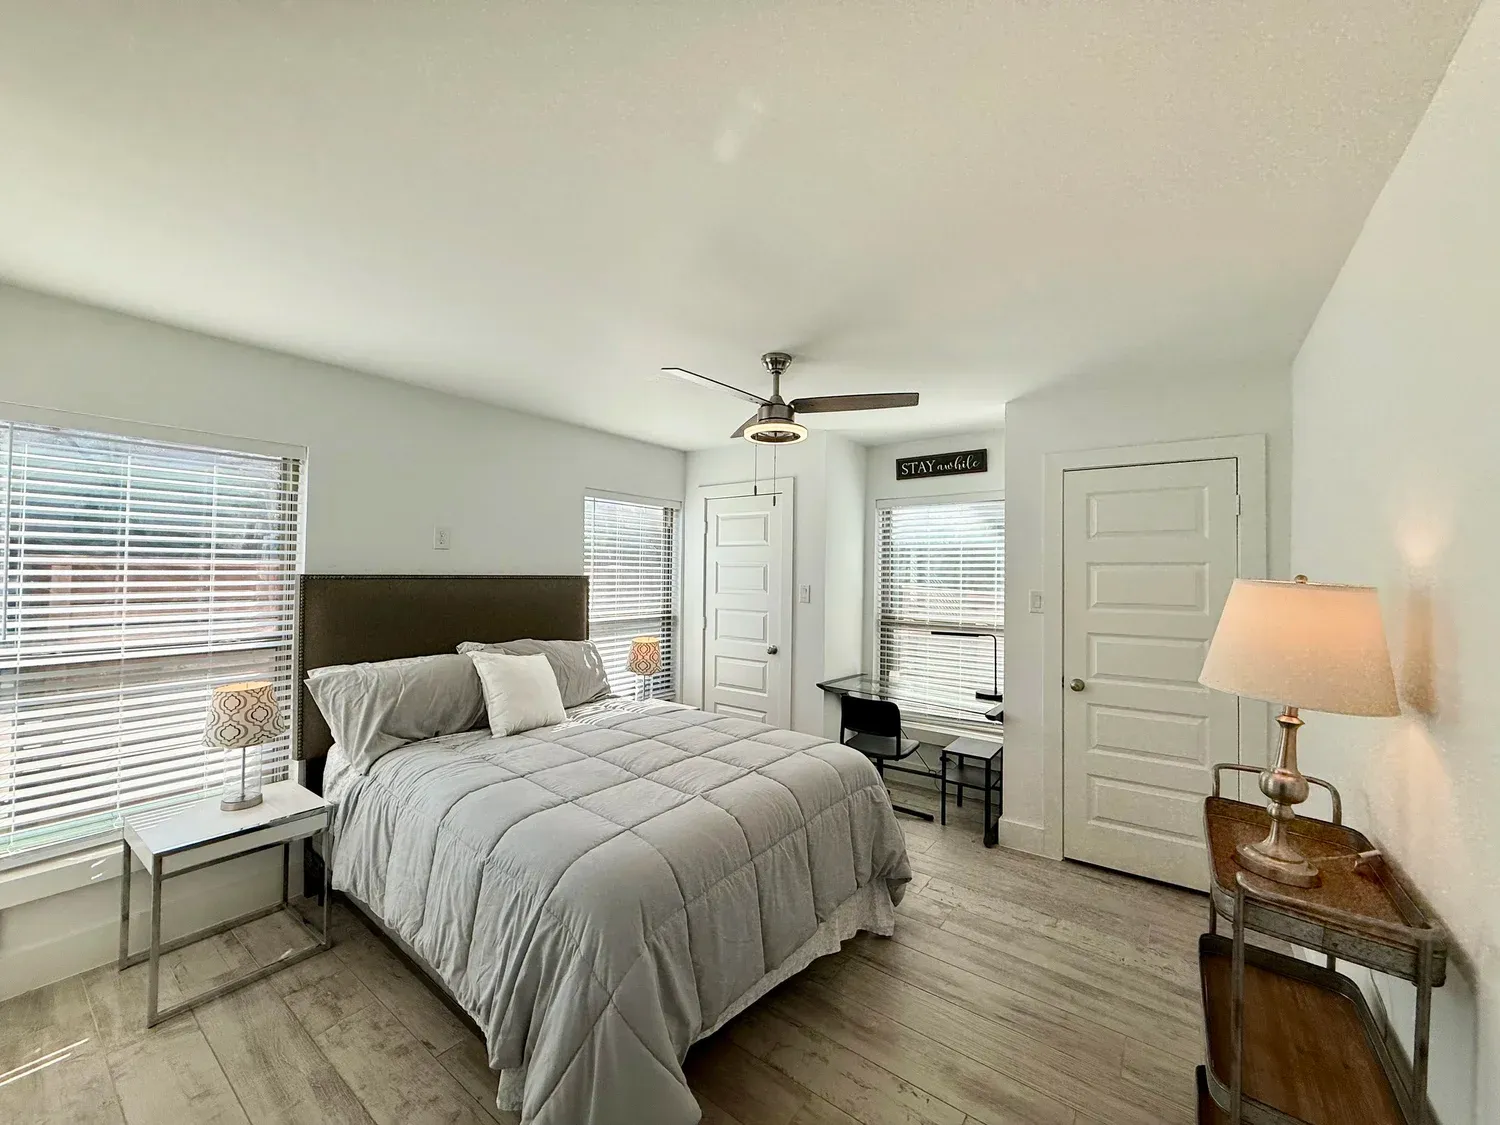
Texas Medical Center Area
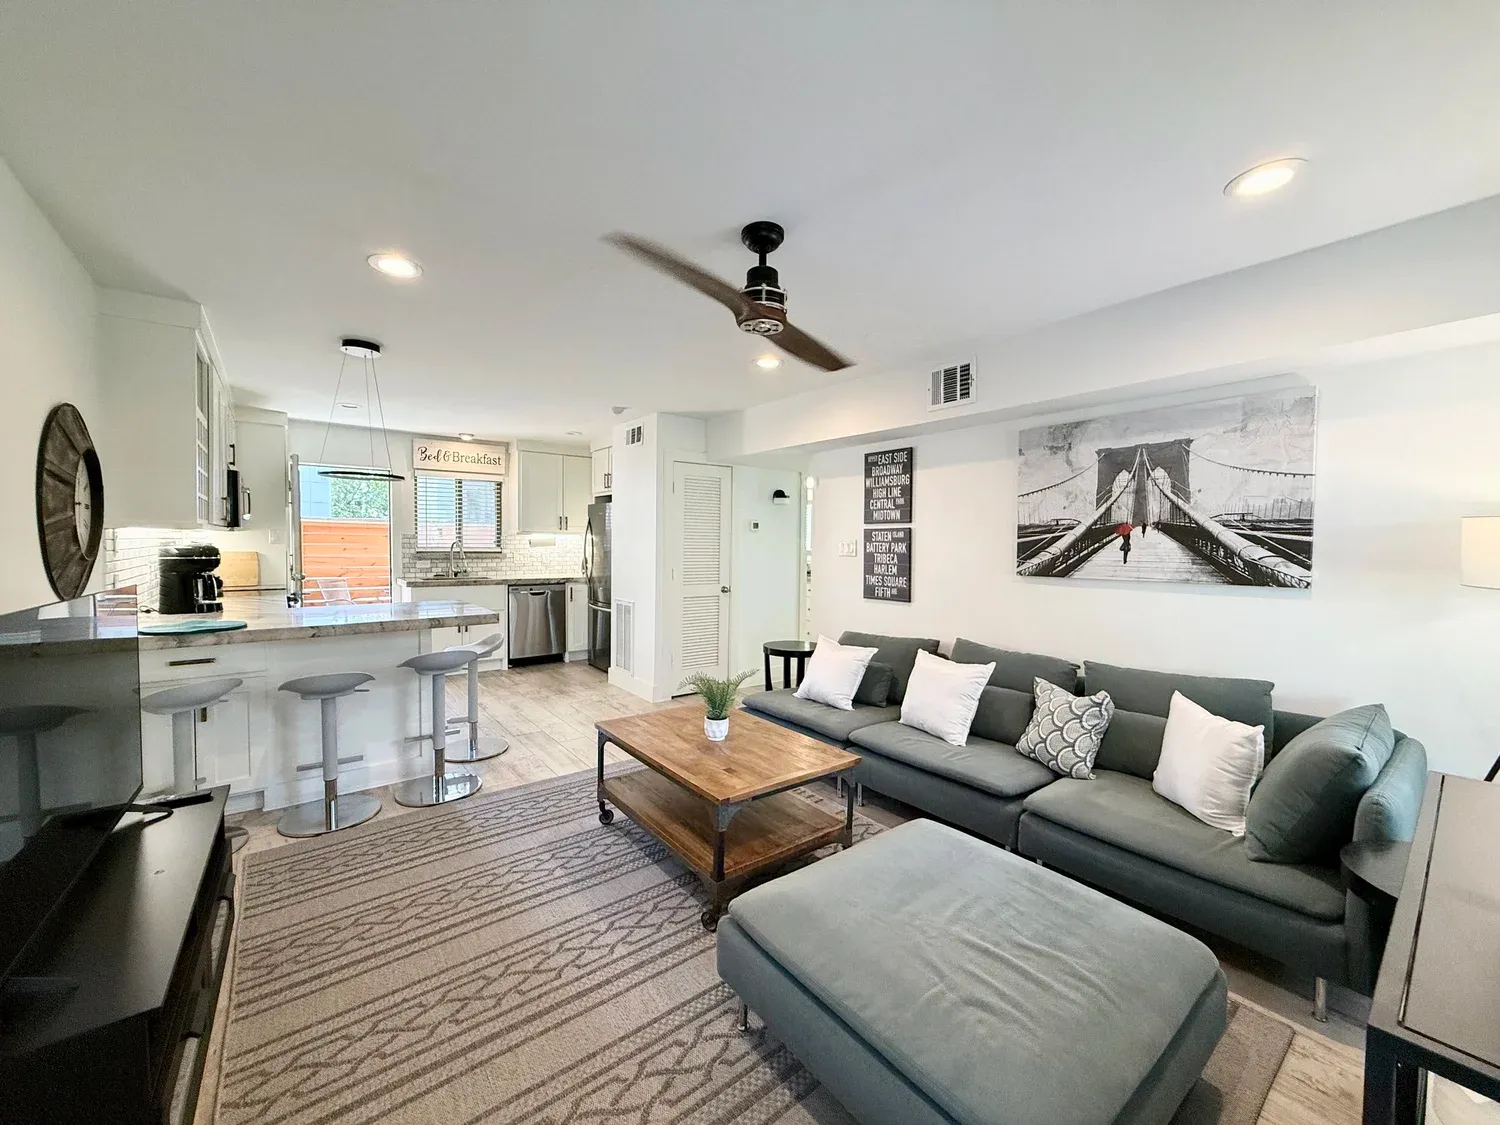
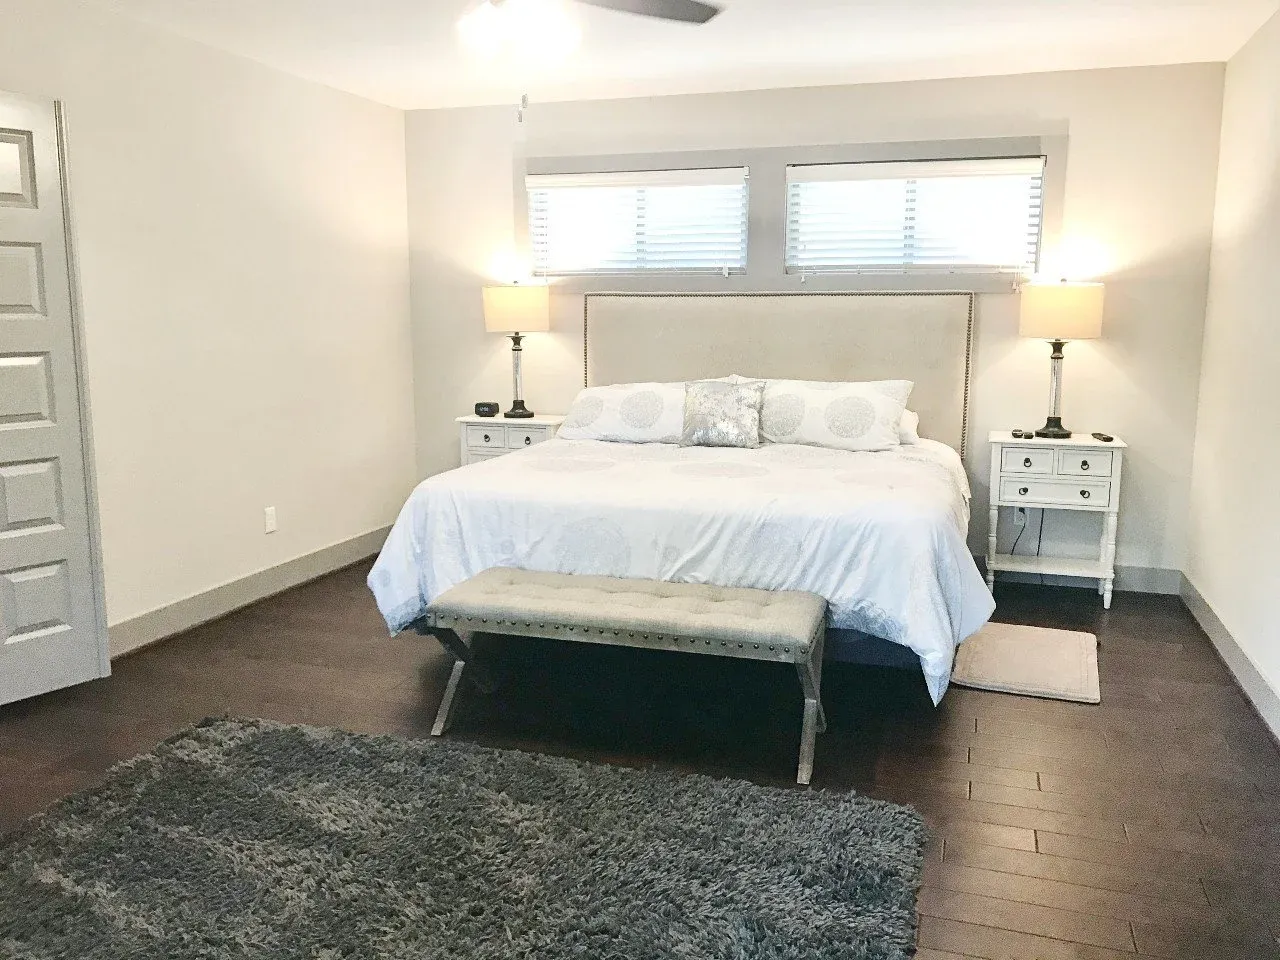
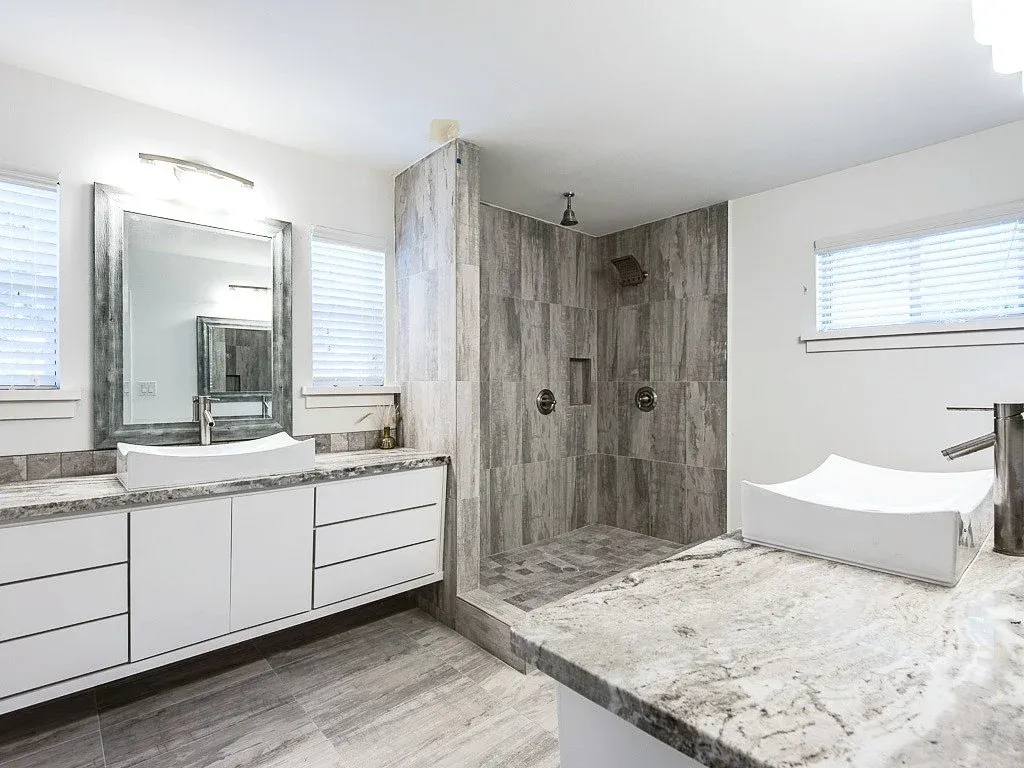
Med Center Retreat
- Ground floor
- Patio
$4,250 per 30 nights
Plus a one-time $350 cleaning fee.
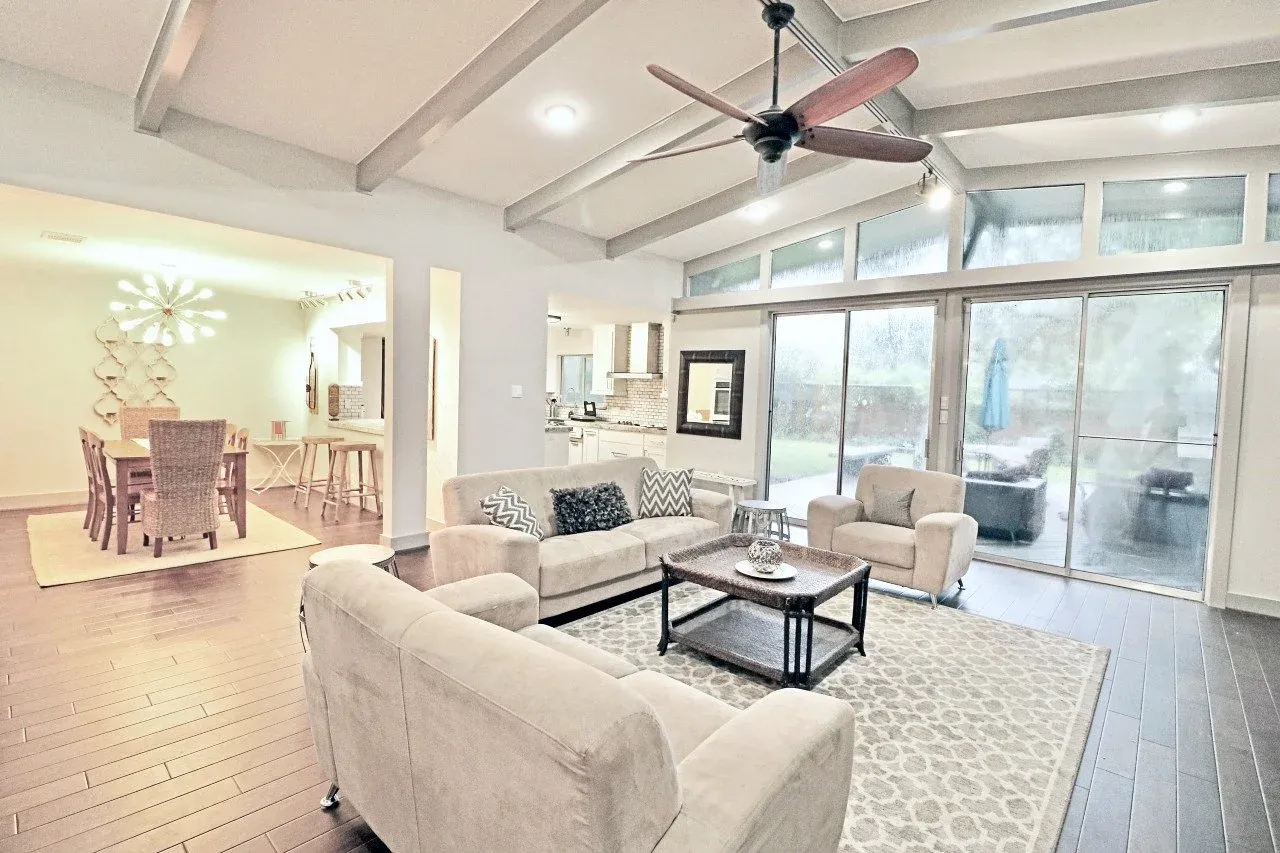
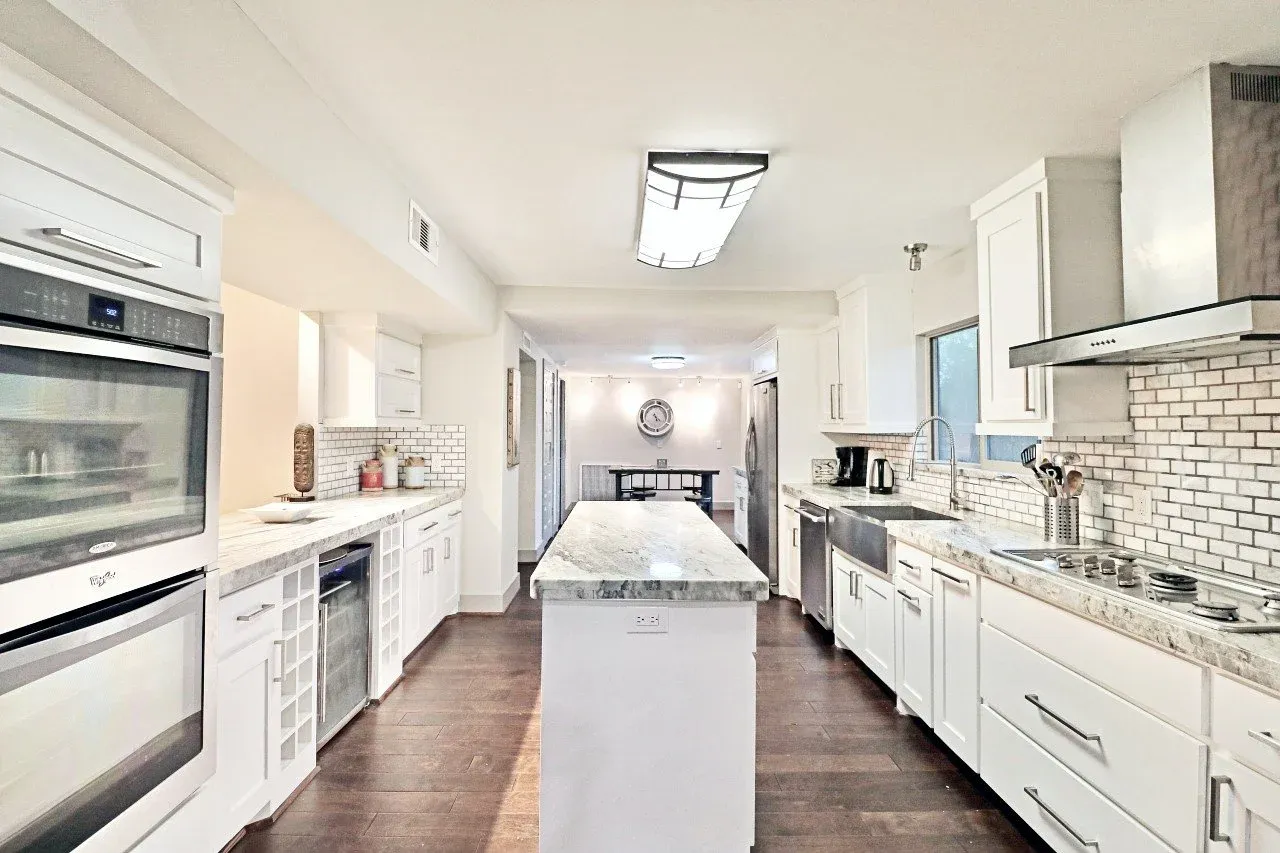
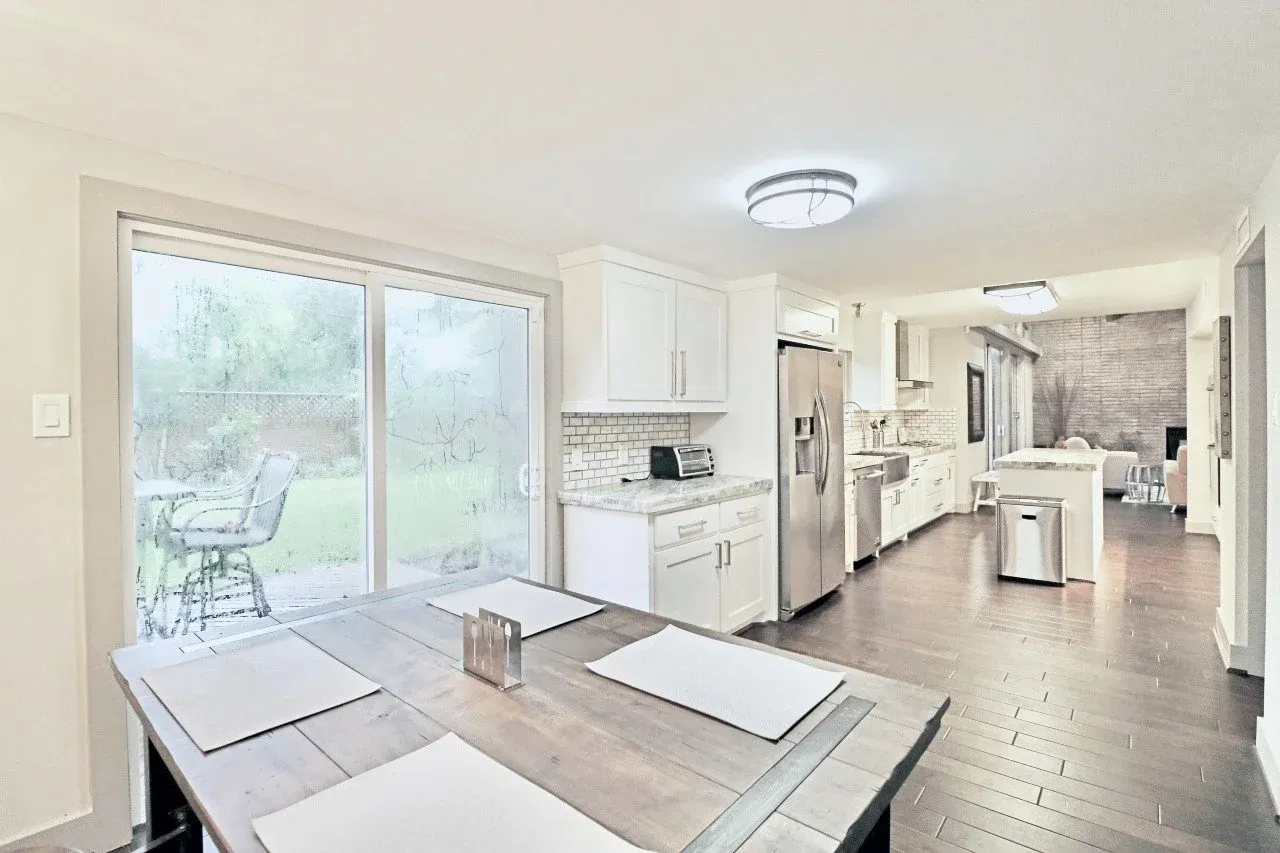
Texas Medical Center Area / Bellaire / Meyerland Area
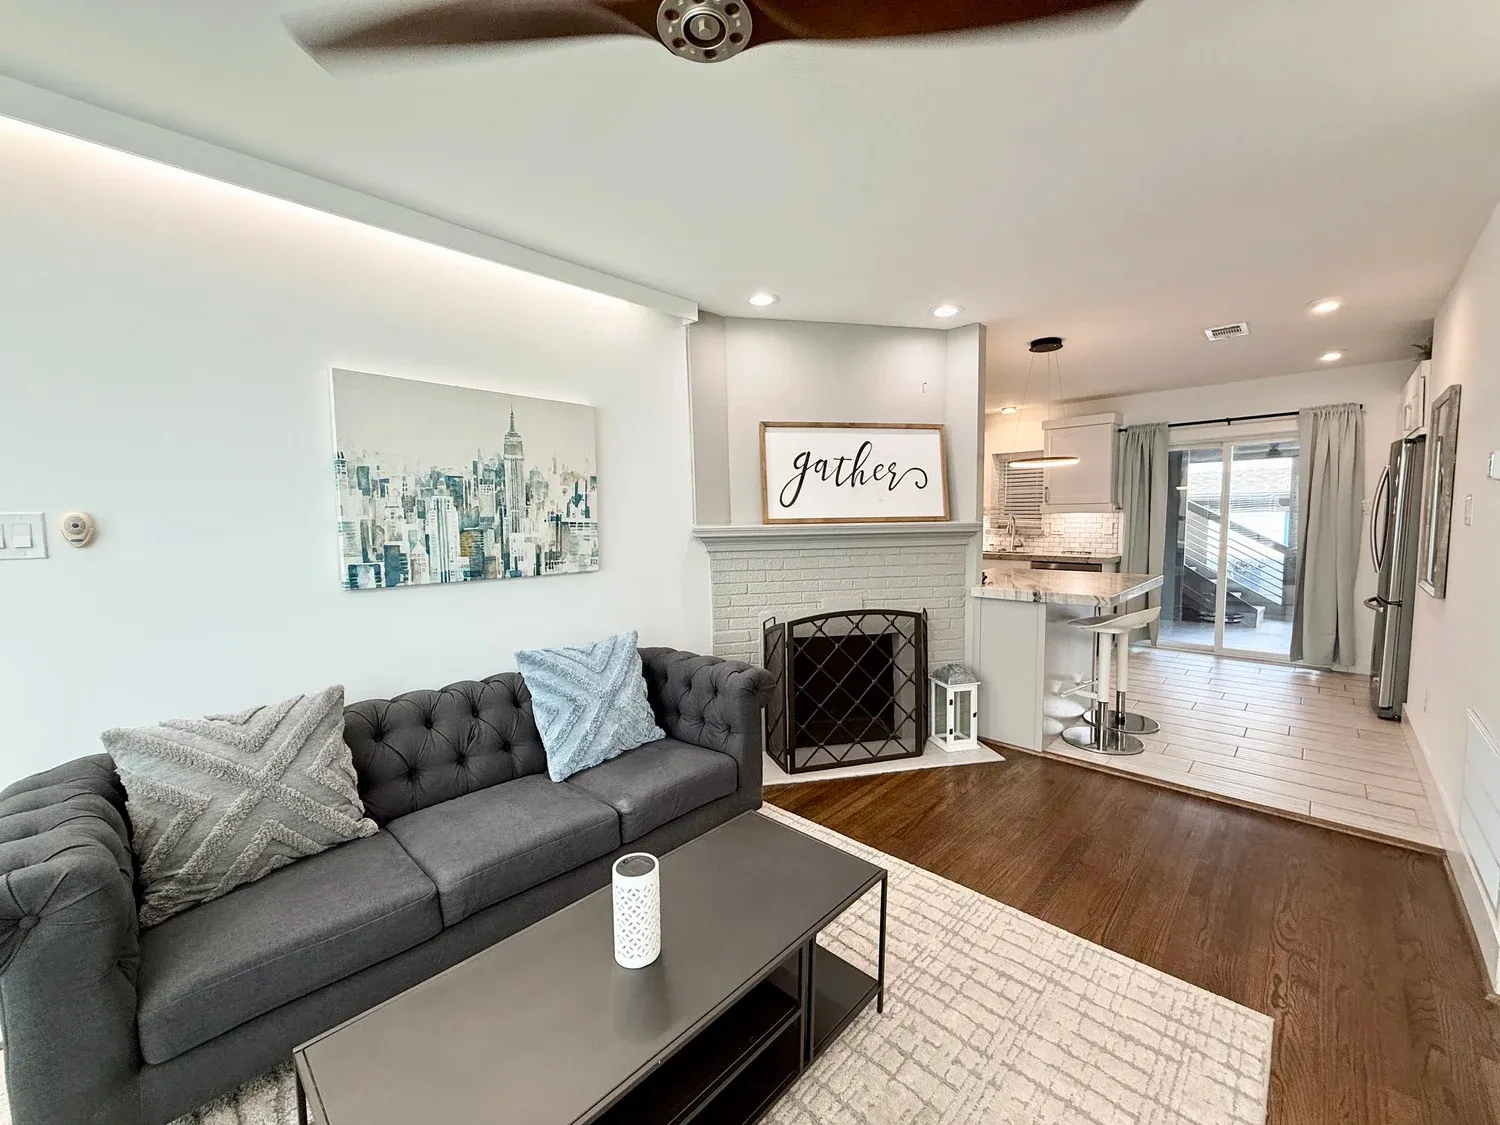
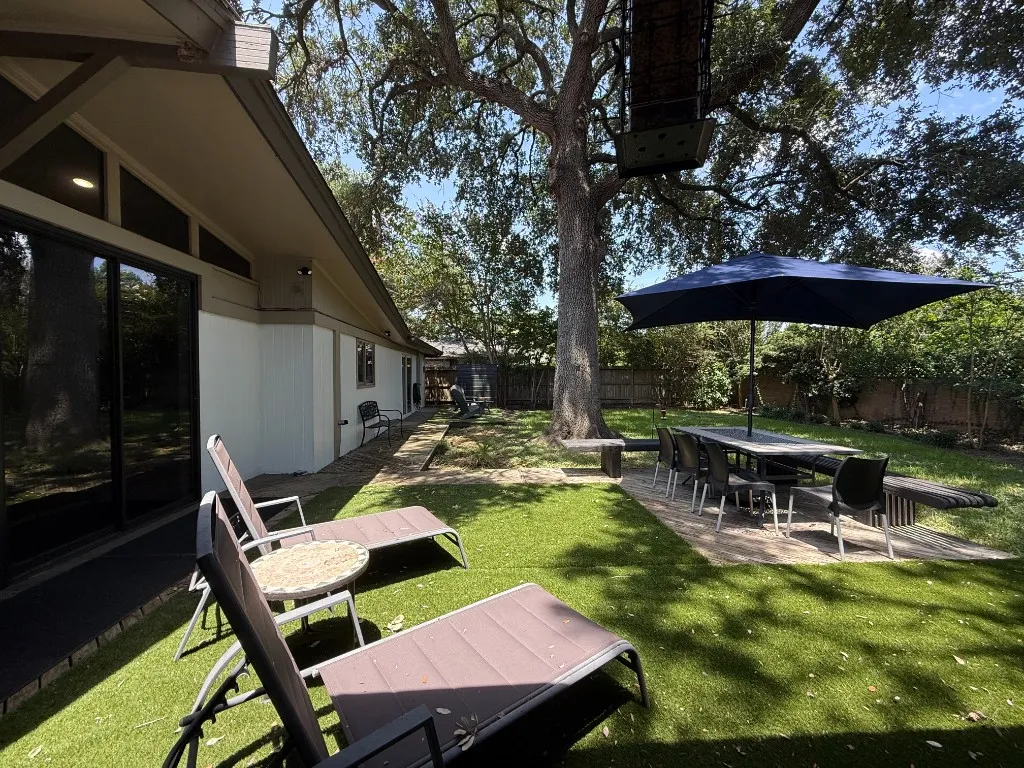
The New Grove
- One story
- Fenced Yard
$7,500 per 30 nights
Plus a one-time $350 cleaning fee.
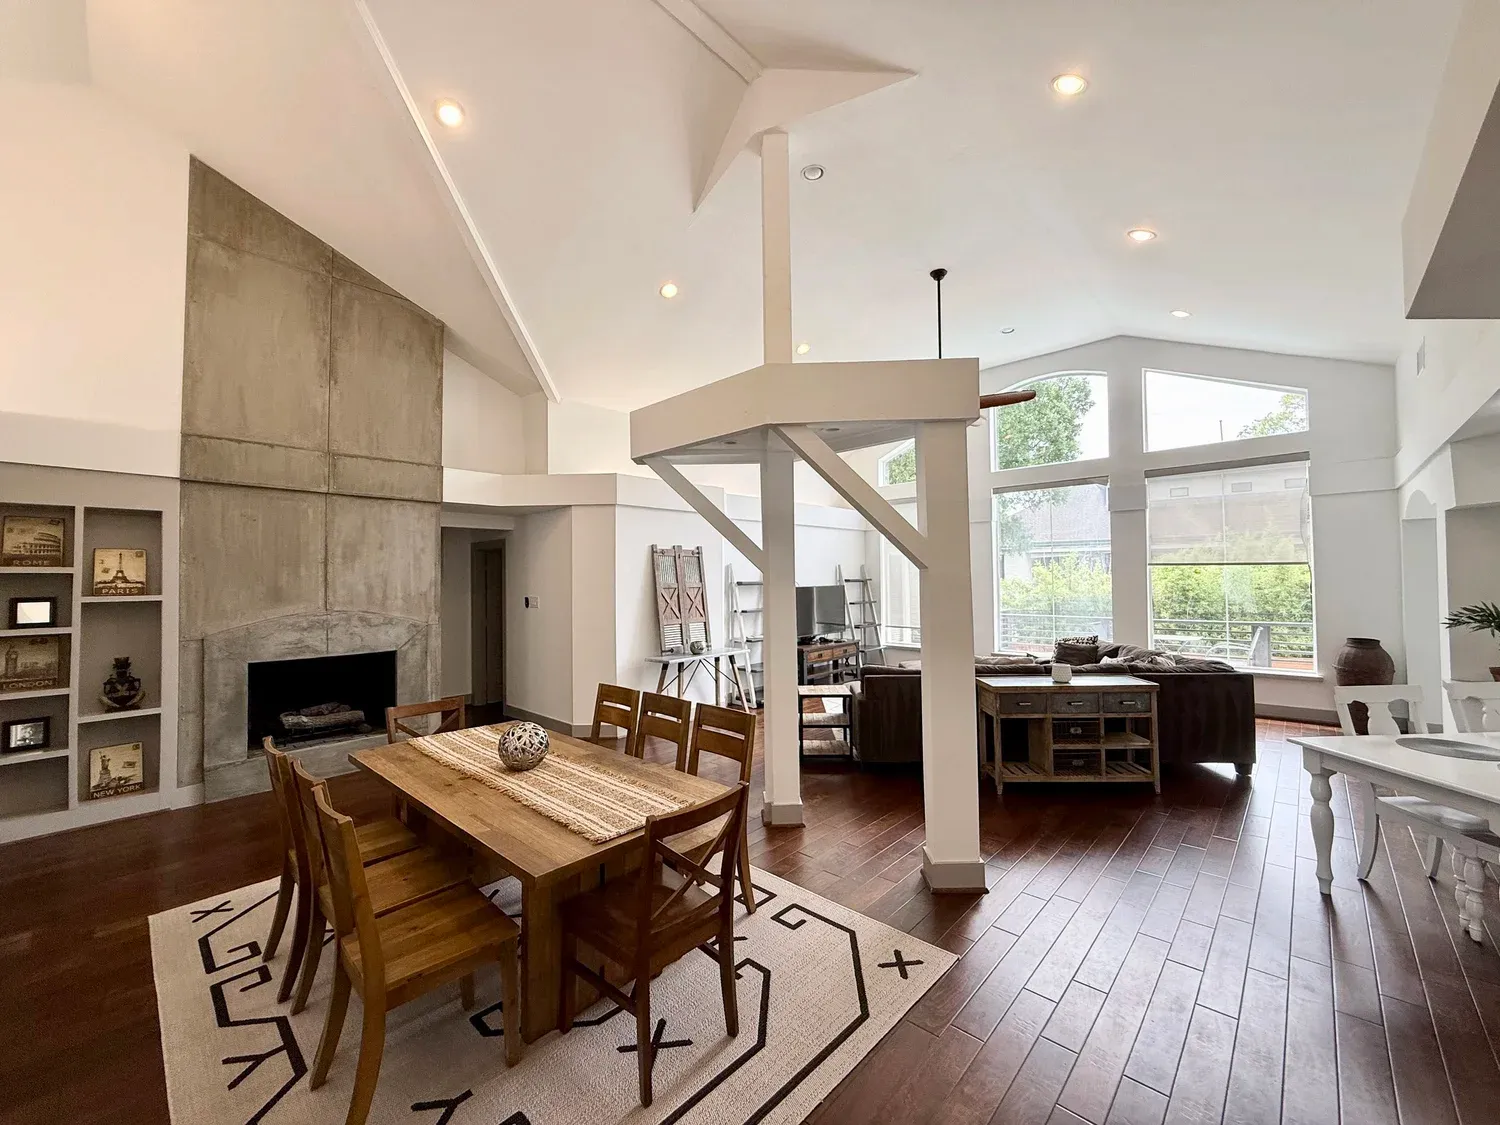
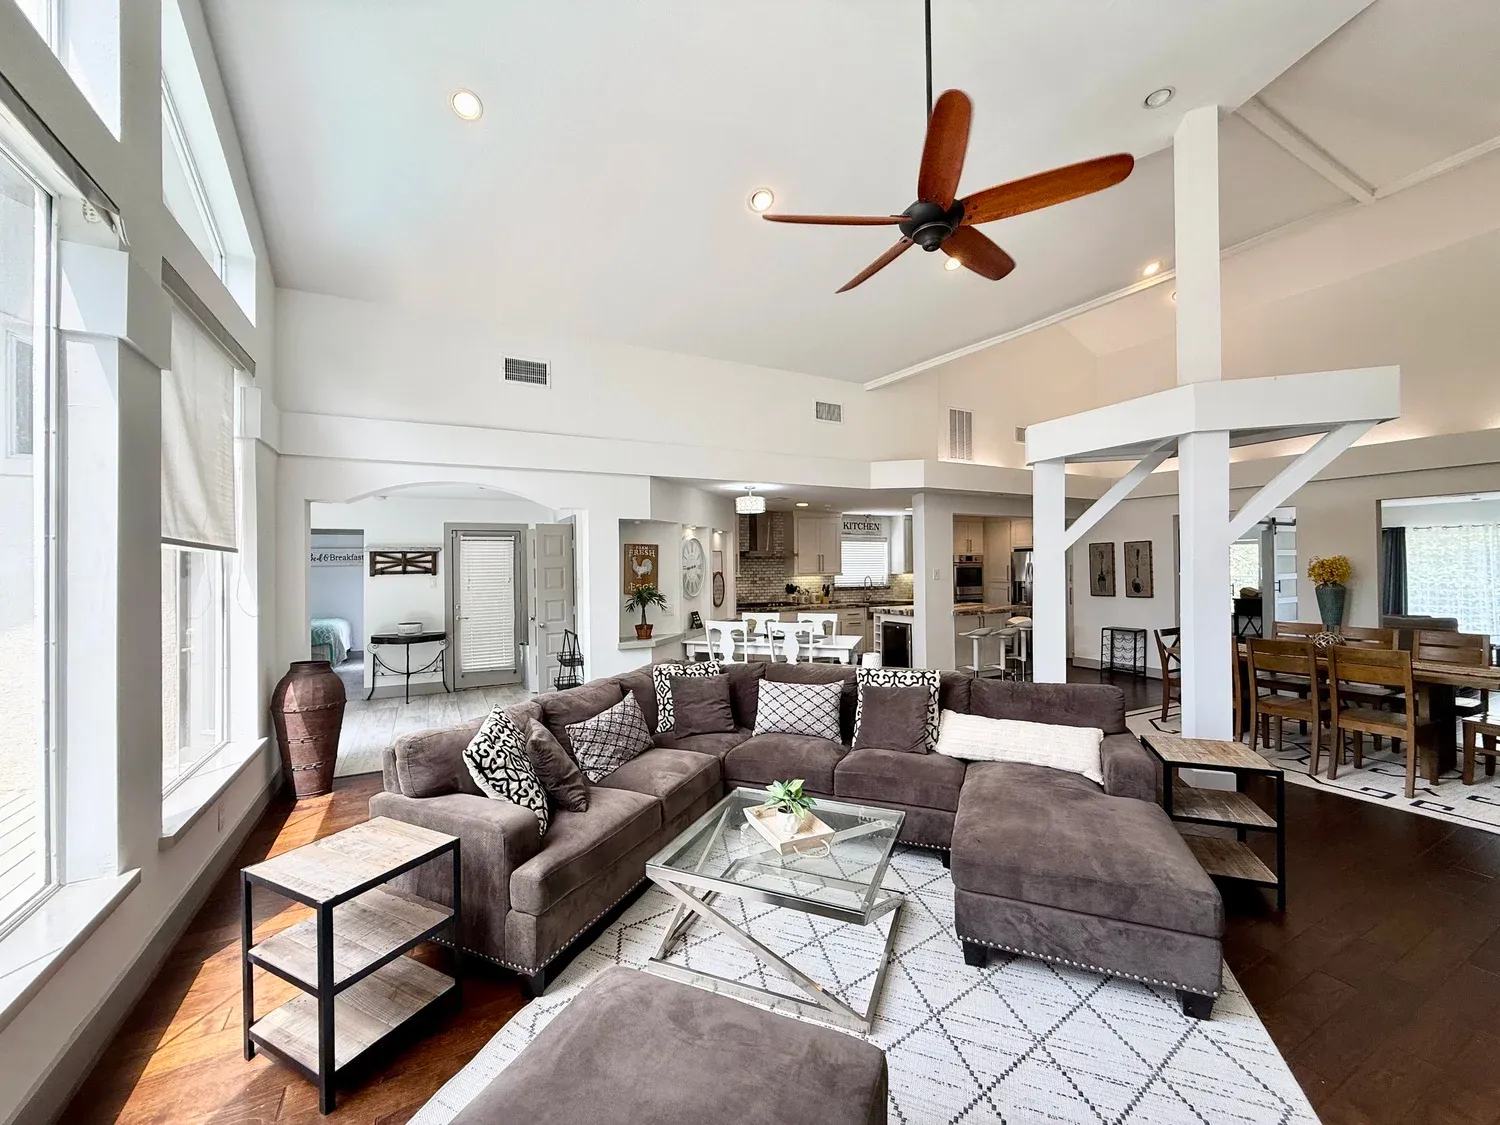
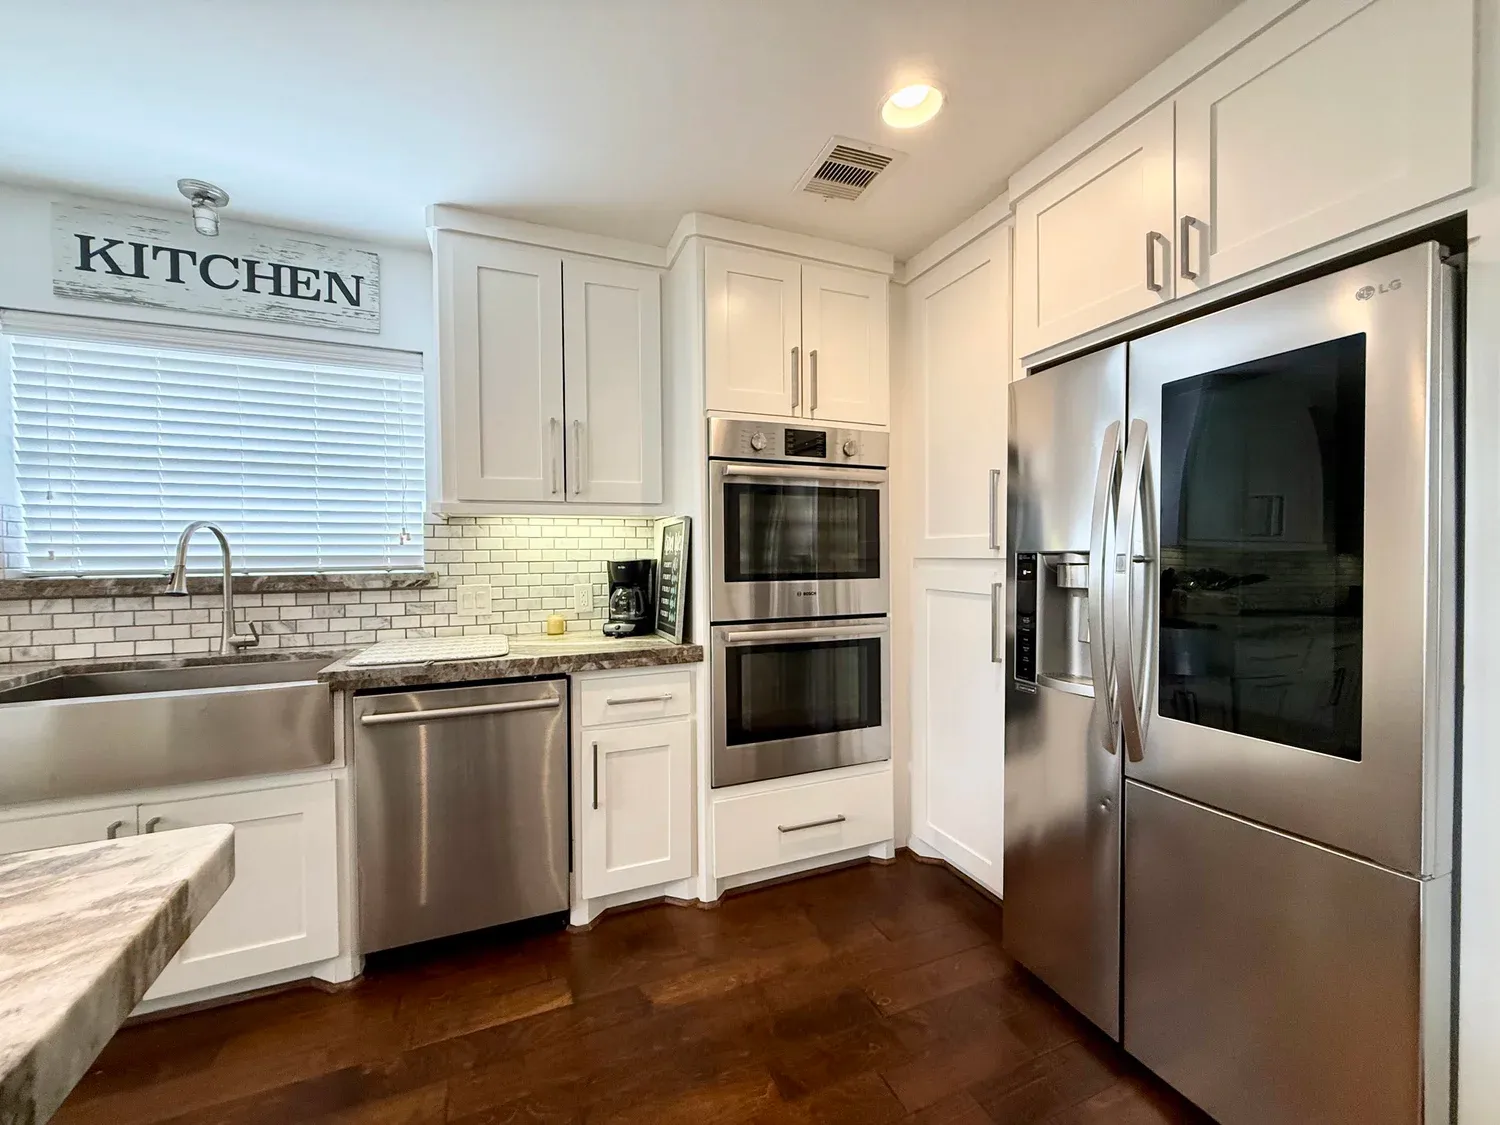
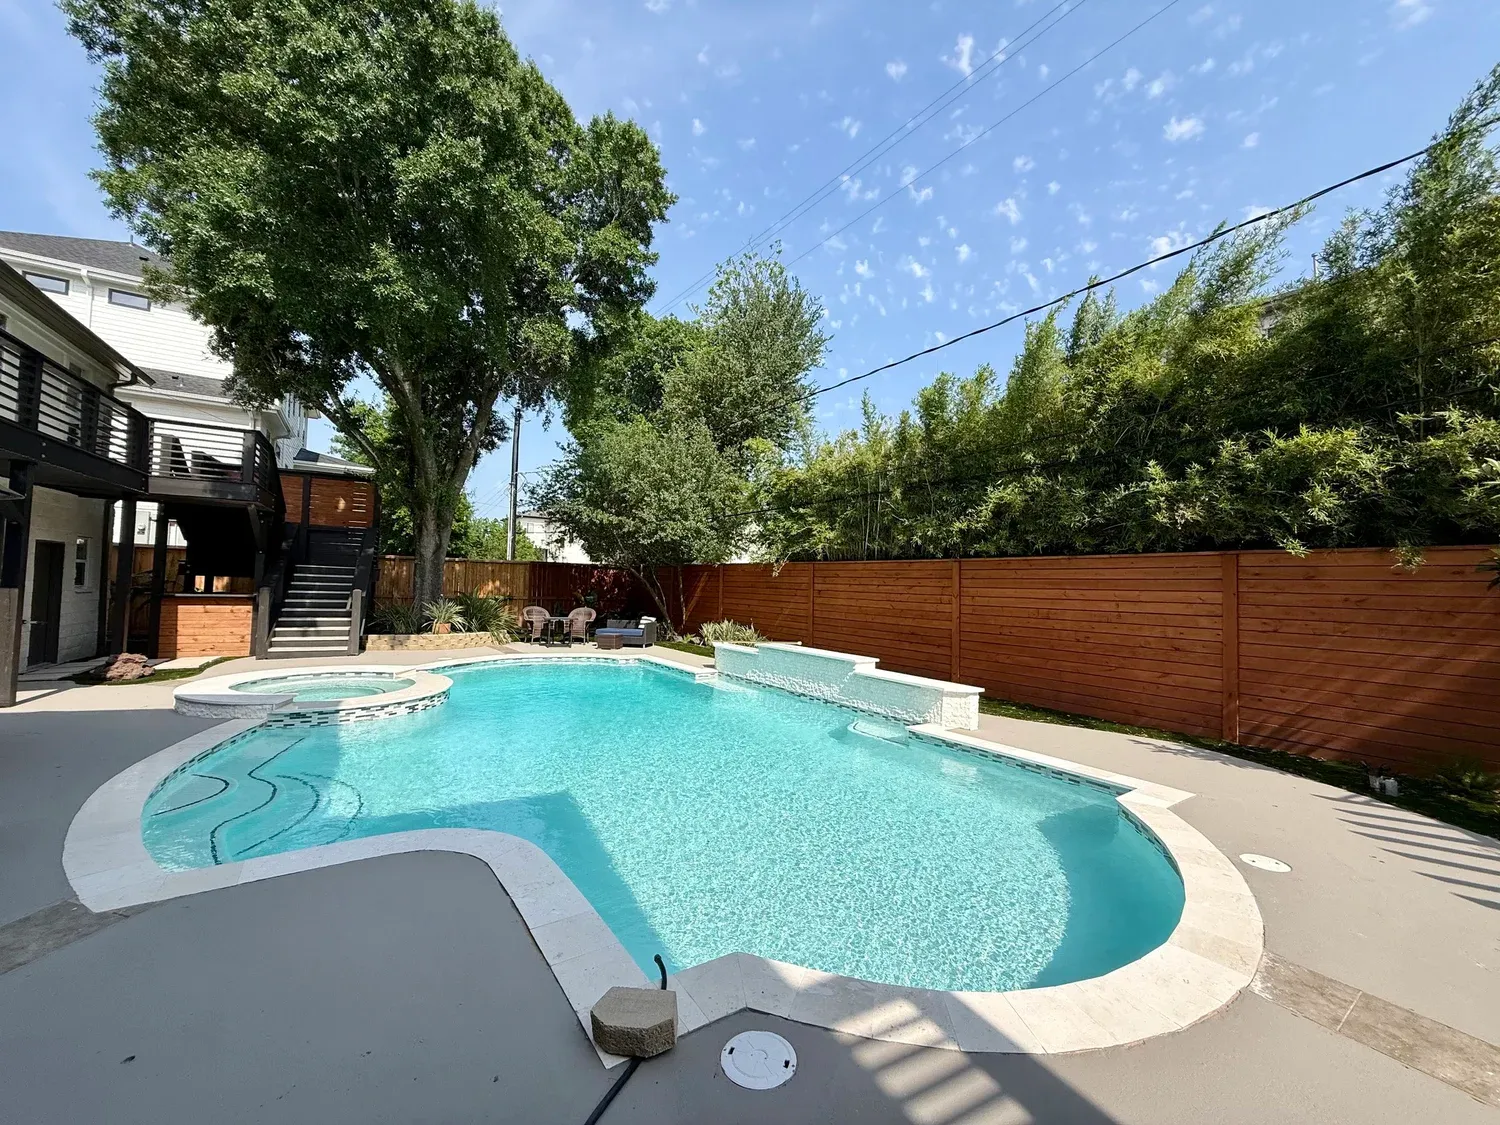
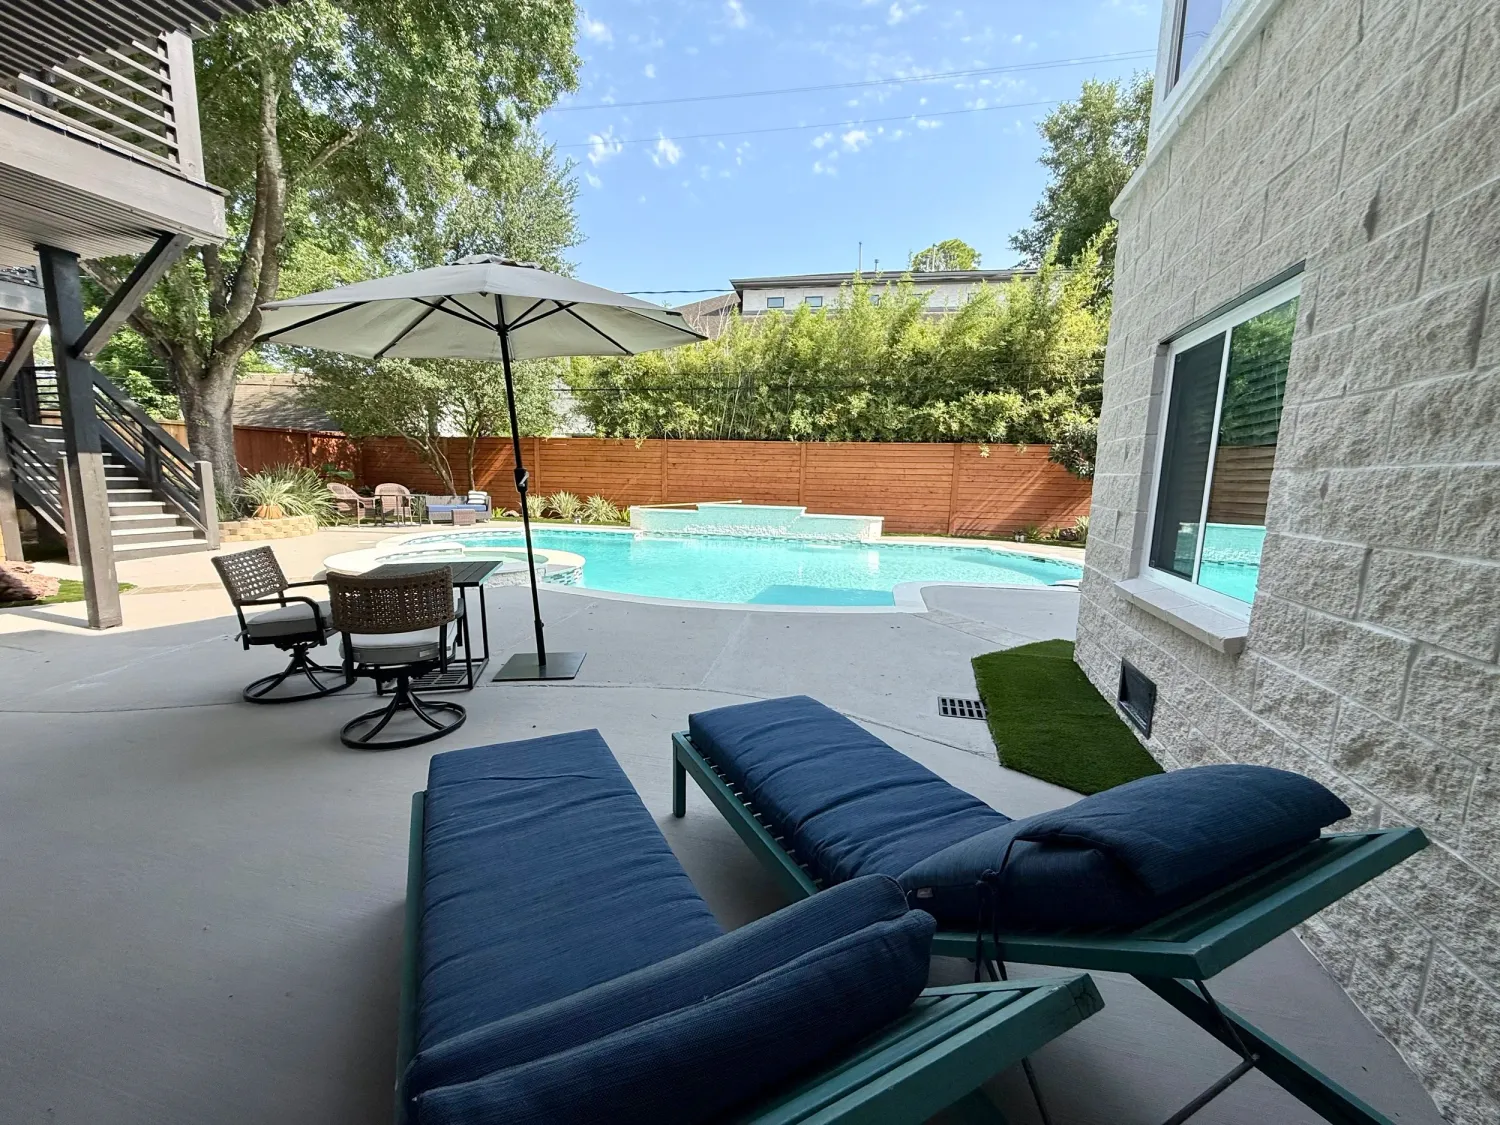
Texas Medical Center Area / Bellaire / Meyerland Area
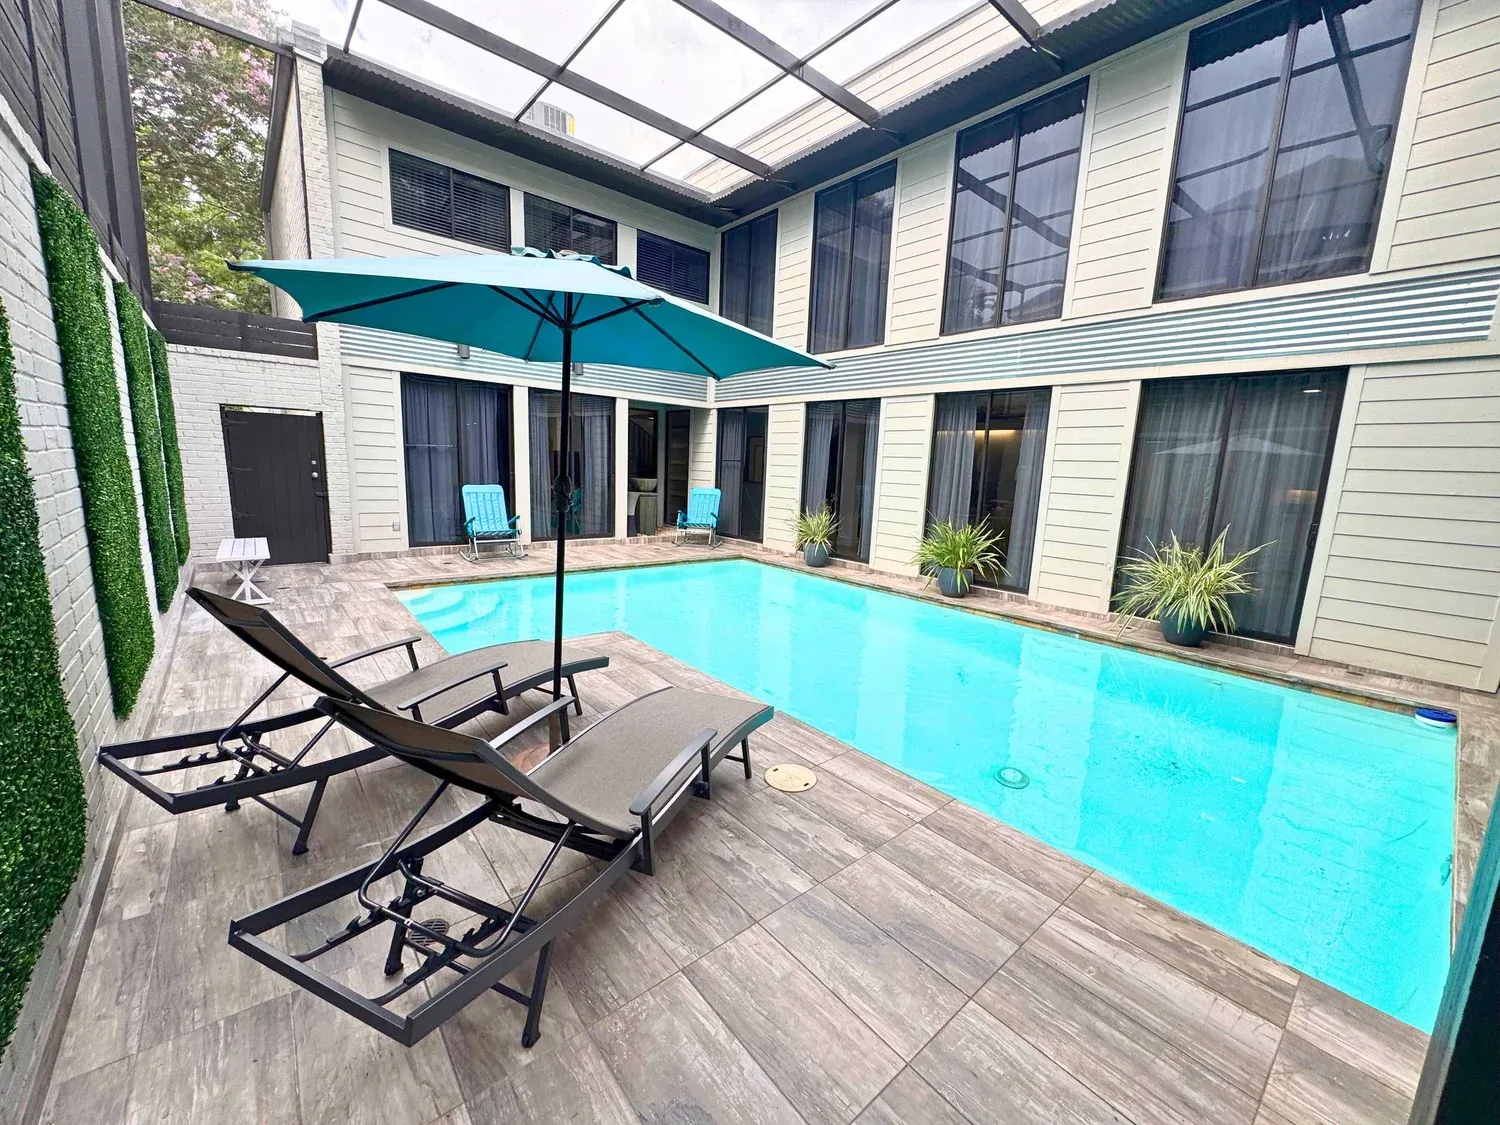
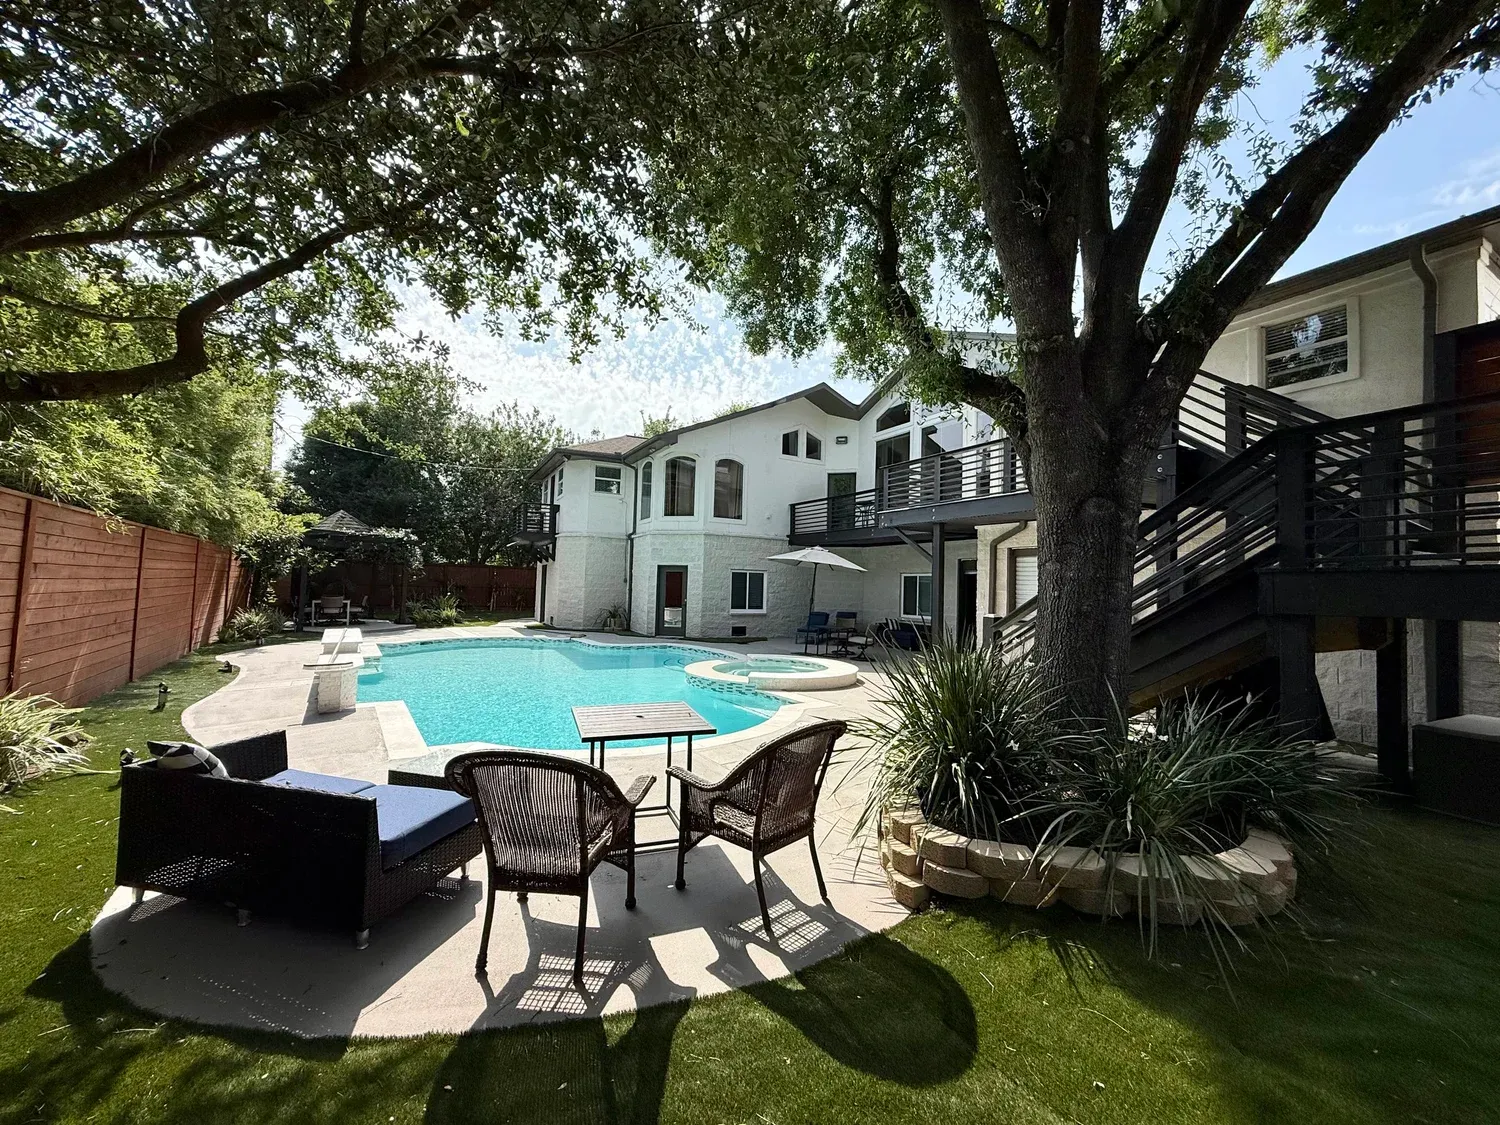
Villa Como
- Two story
- Private Pool
- Fenced Yard
$15,000 per 30 nights
Plus a one-time $350 cleaning fee.
Featured houses and apartments · 30+ night minimum · Confirm dates and current pricing with our team.
A fire, burst pipe, or storm can make a rental impossible to sleep in. The question is whether the renters policy pays for somewhere else to stay, and for how long. The declarations page answers that. This guide explains the coverage people mean when they ask, what usually is and is not paid, and how a Houston furnished home fits once the stay is 30 nights or longer.
Insurance housing compared
| Feature | Luxurway furnished home | Hotel |
|---|---|---|
| Nightly guide | $167–$533 equivalent, 30+ night minimum | Nightly rate plus tax |
| 30-night guide | $5,000–$16,000 | Confirm the full-stay total |
| Kitchen | Full kitchen | Rarely a full kitchen |
| Laundry | In-home | Varies |
| Carrier billing | Send an invoice after the claim number and adjuster contact; the carrier decides whether it pays | Usually a guest folio |
| Term | 30 nights; extensions subject to availability | Nightly |
Luxurway can send an insurance carrier an invoice for Additional Living Expense housing when we have the claim number and adjuster contact. The carrier decides whether it pays. Hotels fit nights before the 30+ night minimum. Catalog rates checked Sep 26, 2026.
The short answer
On many HO-4 renters policies, yes. Coverage D is loss of use. Insurers often call the housing part additional living expense, or ALE. It can pay the extra cost of living somewhere else when a covered peril makes the residence premises uninhabitable.
It does not pay because a move would be more convenient. The loss has to be covered, the unit has to be unfit to live in, and the expense has to be above what you normally spend. The dollar limit, the time limit, and the excluded causes are on your declarations page and in the policy form. Read those before you book a long stay.
What loss of use usually pays
Additional living expense is the increase in your cost of living, not a blank check for a new lifestyle. When the coverage applies, adjusters commonly look at:
- Temporary housing, such as a hotel for the first nights or a furnished house once the repairs will take a month or more
- Extra meal costs when you cannot cook
- Laundry, if you no longer have a washer
- Storage for belongings that have to leave the unit
- Pet boarding, when the temporary place cannot take the animal
- Extra transportation, when the temporary address changes the commute
The policy pays the increase. If you already spend a set amount on rent and food, the carrier looks at what you are spending now that is above that baseline. Keep receipts. A card statement with no note about what it was for is harder to explain later.
What it usually does not pay
Loss of use follows the same covered perils as the rest of the policy. If the cause of loss is excluded, the housing coverage does not step in.
Common gaps:
- Flood damage, which a standard renters policy usually excludes
- Earthquake, unless you bought that coverage
- Wear, mold from long-term neglect, or a maintenance problem the landlord is responsible for and the policy does not cover
- A voluntary move, a lease dispute, or being asked to leave for a reason that is not a covered property loss
- Your normal rent, normal groceries, and other bills you would have paid anyway
- A stay that runs past the dollar limit or the time limit on the declarations page
Landlord insurance covers the building. It does not replace your renters policy, and it does not automatically put you in a hotel. Ask the landlord what they will do about the lease, and ask your own insurer what Coverage D pays.
How to find your limit
Open the declarations page and look for Coverage D, loss of use, or additional living expense. On many renters policies the limit is a percentage of the personal-property coverage (Coverage C), or a stated dollar amount. Some policies also cap the number of months.
Write down three numbers before you choose housing:
- 01The dollar limit
- 02The time limit, if there is one
- 03Your deductible, which usually applies to the property claim and not as a separate housing deductible, but confirm that with the adjuster
If the page is unclear, call the agent and ask them to point at the form number. Do not guess from a blog, including this one.
How to file
- 01Make sure people are safe, then tell the landlord and the insurer.
Give the date, the cause, and whether anyone can sleep there tonight.
- 02Ask the adjuster, in writing if you can, whether loss of use applies and what the limit is.
- 03Use a hotel or a family member for the first nights if the unit is unsafe. A furnished monthly home is the better fit once you know the repairs will run 30 nights or longer.
- 04Save leases, hotel folios, and receipts.
Note which costs are new.
- 05Send the adjuster the address, the monthly rate, what is included, and the dates before you sign a long stay. The carrier decides whether it pays.
Homeowners with a house claim, rather than renters, should use the ALE approval guide. For the broader set of options after a Houston loss, see temporary housing options for insurance claims.
A furnished Houston home once the stay is 30 nights
Hotels work for a few nights. They get expensive, and cramped, when repairs last a month. Insurance housing at Luxurway is a furnished Houston house for a stay of 30 nights or longer. Temporary housing is the same collection when the reason is a remodel or a wait for the unit to be ready.
Apartments are $3,300–$4,250 per 30 nights. Houses range $5,000–$16,000 per 30 nights. Utilities and Wi-Fi are included. A one-time $350 cleaning fee applies.
Send the claim number and the adjuster contact, and the Houston team quotes the stay. Luxurway can send the carrier an invoice. The carrier decides whether it pays. This is not housing the carrier assigns.
Frequently asked questions
Luxurway offers furnished Houston houses for displaced families and Additional Living Expense claims. Stays start at 30 nights. Utilities included. Send the claim number and adjuster contact, and the team quotes the stay. Luxurway can send the carrier an invoice. The carrier decides whether it pays. Call (832) 304-3322, email Info@Luxurway.com, or send dates on the contact form.
Yes. Send the claim number and adjuster contact, and the team quotes a furnished Houston house for Additional Living Expense claims. Luxurway can send the carrier an invoice. The carrier decides whether it pays.
Insurance stays start at 30 nights. If repairs run long, ask for updated dates. The adjuster decides what the claim covers.
Furniture, bedding, towels, a full kitchen, washer and dryer, private parking, utilities, and Wi-Fi. Housekeeping during the stay is extra. Confirm the listing and any pet fees with the Houston team.
Pets must be disclosed and approved before booking. A nonrefundable pet fee applies. Ask our team to confirm the house rules for your dates. Assistance animals, including service and emotional support animals, are not pets. They are welcome in every home, including homes listed as no pets, with no pet fee or pet deposit.
Send your check-in date on the form. Call (832) 304-3322 or email Info@Luxurway.com to share guests, neighborhood, pets, and budget. Email the claim number and adjuster contact to Info@Luxurway.com. The team quotes the stay.